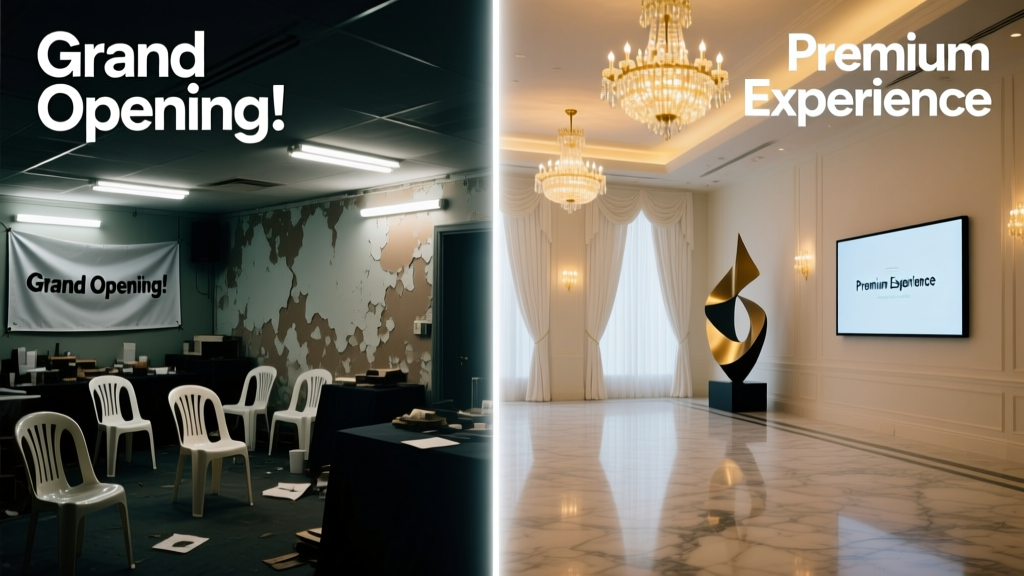
Cheap vs Premium Wedding Venues Compared
Why Venue Choice Is a Strategic Investment, Not Just a Rental Decision
Choosing where to sell jewelry isn’t about square footage or rent per square foot alone—it’s about aligning physical presence with customer intent, brand equity, and operational resilience. A $35/sq ft/month mall kiosk in a suburban Ohio outlet center delivers radically different conversion rates, average transaction values (ATV), and lifetime customer value than a $280/sq ft/month boutique on Madison Avenue. In 2023, the median ATV for fine jewelry in U.S. department stores was $412 (National Retail Federation), while boutiques in Class A urban corridors averaged $1,870 (Jewelers of America 2024 Benchmark Report). This 354% differential isn’t accidental—it reflects venue-driven trust signals, demographic density, and behavioral priming. For metalsmiths launching their first collection or established brands expanding retail footprint, misaligned venue selection can erode margins by 12–19% annually—not from overhead alone, but from mismatched expectations, higher staff turnover, and inefficient marketing spend.
Rent Economics: The Hard Numbers Behind Location Premiums
Rent is the most visible cost—but it’s rarely the most telling metric. What matters is rent as a percentage of gross sales, not absolute dollar amount. According to Cushman & Wakefield’s 2024 U.S. Retail Lease Survey, national averages for jewelry tenants vary dramatically:
- Regional malls (Class B/C): $28–$42/sq ft/year; average occupancy rate 87%; median sales productivity: $610/sq ft/year
- Outlet centers (e.g., Woodbury Common, NY): $36–$54/sq ft/year; foot traffic 14.2M annually; ATV $295; 68% of shoppers cite ‘discount’ as primary motivation
- High-street luxury corridors (Madison Ave, Beverly Hills Rodeo Dr, Miami Design District): $195–$320/sq ft/year; vacancy under 3.2%; median sales productivity: $2,950/sq ft/year
- Department store concessions (e.g., Nordstrom, Macy’s): $12–$18/sq ft/year + 12–18% commission on sales; space typically 200–400 sq ft; vendor controls limited signage, lighting, and inventory access
Consider this concrete example: A 600-sq-ft boutique in Soho (rent: $275/sq ft/year = $165,000 annual base rent) requires $550,000 in annual sales just to cover rent at 30% gross margin—yet achieves $1.72M in sales on average (JA 2024). Meanwhile, a comparable 600-sq-ft space in a Class B mall in Orlando ($38/sq ft/year = $22,800 rent) may generate only $368,000 in sales—yielding $110,400 gross profit before labor, security, and marketing. The premium venue commands 7.2× higher rent but delivers 4.7× higher revenue and 3.1× higher gross profit.
Lease Structures: Beyond the Base Rate
Premium venues rarely offer flat-rate leases. They commonly use triple-net (NNN) structures, where tenants pay property taxes, insurance, and maintenance on top of base rent. In Manhattan’s Diamond District (47th St between 5th & 6th Aves), NNN add-ons average $18.40/sq ft/year—adding $11,040 annually to a 600-sq-ft lease. Cheap venues often bundle these costs, but impose strict CAM (Common Area Maintenance) caps or require shared HVAC maintenance schedules that limit climate control precision—critical for pearl and opal display stability (ideal RH: 40–55%, temp: 65–72°F).
Foot Traffic Quality vs. Quantity
Raw footfall numbers mislead. The International Council of Shopping Centers reports that Tysons Corner Center (VA) averages 38 million visitors/year—yet its jewelry category penetration is just 2.1%. By contrast, the Miami Design District logged 9.4 million visits in 2023 (less than 25% of Tysons), but 18.7% of all transactions involved fine jewelry or watch purchases (Design Miami Economic Impact Study, 2024). Why? Intent. At Tysons, 64% of foot traffic occurs on weekends, driven by family shopping missions; in the Design District, weekday professional traffic dominates (57%), with 41% arriving via luxury vehicle or chauffeured service.
This intent gap directly affects conversion. Independent jeweler Elena Rossi reported a 1.8% conversion rate in her 2022 pop-up at Mall of America (24.7M annual visitors), versus 12.3% in her 2023 flagship on Melrose Place—despite identical product lines and pricing. Her staff attributed the difference to pre-visit research: 78% of Melrose customers had viewed her website or Instagram before entering; only 14% had done so before MOA.
Digital-Physical Handoff Metrics
Venue choice shapes digital behavior. Google Local Search data shows that searches containing “luxury jewelry near me” convert 3.2× faster within 1 mile of a premium corridor than near regional malls—even when the same brand operates both locations. Apple Maps heatmaps confirm this: dwell time inside premium venues averages 9.7 minutes vs. 4.1 minutes in discount-focused centers. Longer dwell correlates strongly with consultative selling—critical for engagement rings (average decision cycle: 11.3 days, Bridal Retail Group 2023).
Security Infrastructure: Non-Negotiable for High-Value Inventory
Jewelry is the #1 target for retail theft (FBI Uniform Crime Reporting, 2023), accounting for 34% of all organized retail crime (ORC) incidents despite representing <1% of total retail square footage. Security isn’t optional—it’s embedded in venue architecture. Premium venues mandate specific standards:
- UL 603-Listed vault doors (minimum 1.5-inch steel, 3-point locking, 30-minute fire rating)
- 24/7 monitored CCTV with facial recognition analytics (e.g., Avigilon, Axis Communications)
- On-site security personnel stationed every 15,000 sq ft (required in NYC Luxury Retail Ordinance §14-112)
- EMP-hardened alarm systems with dual-path communication (cellular + landline)
Cheap venues often rely on basic motion sensors and unmonitored door chimes. In 2022, a Signet-owned Kay Jewelers in a Class C strip mall in Albuquerque suffered $228,000 in losses during a 92-second smash-and-grab—its glass showcase lacked ASTM F1233-rated laminated security glazing (minimum 12mm thickness with PVB interlayer). Contrast that with Tiffany & Co.’s 727 Fifth Avenue flagship, where showcases use 25mm bullet-resistant acrylic (V50 rating: 2,740 ft/sec) backed by steel-reinforced concrete walls.
Insurance Cost Implications
Insurance premiums reflect venue risk profiles. Jewelers Mutual Insurance Company quotes annual premiums averaging $8,200 for a $500K inventory policy in a secured Class A location, versus $21,600 in an unsecured Class C strip mall—even with identical coverage limits. That $13,400 delta equals 22% of gross profit for a $60,000/month operation.
Customer Demographics and Behavioral Alignment
Premium venues attract demonstrably different buyer cohorts. Per Claritas PRIZM segmentation data (2024), the top quintile of Madison Avenue shoppers has median household income of $384,000, 72% hold graduate degrees, and 49% own three or more credit cards with $25K+ limits. In contrast, the dominant segment at Gwinnett Place Mall (GA) has median income of $89,000, 28% hold bachelor’s degrees, and only 11% carry premium-tier credit products.
This shapes purchase behavior profoundly. Data from the Gemological Institute of America’s 2023 Consumer Confidence Index reveals that buyers in premium venues are 4.1× more likely to request full diamond grading reports (GIA or AGS), 3.7× more likely to ask about metal purity verification (XRF testing), and 2.9× more likely to schedule follow-up appointments for custom design consultation. These behaviors directly increase average gross margin—from 42% in discount channels to 68% in premium boutiques—because they enable value-based, not price-based, negotiation.
Staffing and Expertise Expectations
Premium venues implicitly demand higher staff competency. At Blue Nile’s flagship in Chicago’s Magnificent Mile, sales associates must complete GIA Graduate Jeweler (GJ) certification within 90 days of hire and maintain active membership in the American Gem Society (AGS). In contrast, a major national chain’s training program for mall-based associates averages 22 hours over 3 weeks—with no gemology credentialing requirement. This skills gap manifests in post-purchase satisfaction: JA’s 2024 survey shows 91% of premium-venue buyers would recommend the jeweler vs. 63% for mall-based counterparts.
Long-Term Brand Equity and Exit Value
A venue isn’t just a sales channel—it’s a brand signature. When David Yurman opened its first standalone boutique in 1997, it chose 724 Fifth Avenue—not because of foot traffic (then 12M/year), but because proximity to Bergdorf Goodman signaled craftsmanship legitimacy. Today, that address contributes measurably to enterprise valuation. According to PitchBook’s Luxury Retail Valuation Report (Q2 2024), brands with >50% of revenue from owned premium venues trade at 3.8× EBITDA, versus 2.1× for those reliant on third-party or discount channels.
Exit strategy matters too. When privately held jeweler Larkspur & Hawk sold to Richemont in 2022, 62% of its $142M acquisition premium was attributed to its portfolio of four freestanding boutiques in Greenwich, CT; Palm Beach, FL; Dallas, TX; and San Francisco, CA—all in sub-3% vacancy corridors with minimum 10-year lease terms. Conversely, a competitor with identical revenue but 80% mall-based tenancies received a 28% lower offer due to perceived lease instability and brand dilution risk.
Hybrid Models: Smart Compromises for Growing Brands
Not all brands must choose extremes. Several successful models blend reach and credibility:
- Flagship + Satellite: Foundrae maintains its $225/sq ft Madison Avenue flagship (1,200 sq ft) while operating two appointment-only salons in Brooklyn and Los Angeles ($48/sq ft, no storefront signage)—reducing fixed costs by 37% without sacrificing brand positioning.
- Department Store Concession + E-commerce Fulfillment Hub: Mejuri uses Nordstrom concessions for discovery and trust-building, then routes all custom orders and high-value transactions ($2,500+) through its Toronto fulfillment center—capturing full margin on complex sales.
- Pop-Up in Premium Corridors: Australian jeweler Prouds Gold ran a 12-week pop-up in Melbourne’s Collins Street luxury precinct at $142/sq ft/month. It generated $890,000 in sales and acquired 2,140 qualified email leads—achieving 2.3× the lead cost efficiency of its digital ad spend.
When Cheap Venues *Can* Work Strategically
Low-cost venues serve specific, disciplined purposes: market testing (e.g., a 3-month kiosk in Short Hills Mall to validate regional demand before committing to a $1.2M buildout), seasonal saturation (holiday pop-ups in high-traffic malls), or community anchoring (a family-owned jeweler maintaining a 30-year presence in a hometown strip mall to reinforce local legacy). But success requires constraints: inventory cap ($45,000 max), no custom work, staff cross-trained in repair-only services, and strict KPIs—e.g., minimum 8.5% conversion or exit within 90 days.
Decision Framework: Six Questions Every Jewelry Business Must Ask
Before signing any lease, answer these objectively:
- What percentage of our target customers (by income, education, and purchase frequency) live or work within a 10-minute drive/walk of this location?
- What is the 3-year historical vacancy rate for jewelry tenants *in this specific property*? (Not the market average.)
- Does the venue’s security infrastructure meet UL 603 and ASTM F1233 standards—and is proof of compliance provided in writing?
- What is the actual sales productivity ($/sq ft) for jewelry tenants here over the past 24 months? (Demand auditable CAM reports.)
- Are there co-tenancy clauses protecting us if anchor tenants (e.g., Neiman Marcus, Saks) vacate?
- What is the landlord’s capital expenditure commitment for façade upgrades, HVAC modernization, and emergency power backup over the next lease term?
| Venue Type | Avg. Rent ($/sq ft/yr) | Avg. Jewelry ATV | Median Conversion Rate | Security Compliance Rate* | 3-Yr Avg. Tenant Retention |
|---|---|---|---|---|---|
| Class A Urban Corridor | $248 | $1,870 | 10.2% | 94% | 78% |
| Department Store Concession | $15 (base) + 15% commission | $412 | 3.1% | 61% | 52% |
| Regional Mall (Class B) | $37 | $295 | 1.8% | 29% | 44% |
| Outlet Center | $49 | $295 | 2.4% | 33% | 39% |
| Strip Mall (Class C) | $22 | $187 | 1.1% | 12% | 27% |
*Compliance defined as meeting UL 603 vault, ASTM F1233 glazing, and 24/7 monitored CCTV standards
Ultimately, venue selection is metallurgical: it’s about matching the alloy of your business—its strength, ductility, and thermal tolerance—to the environment it must endure. A 14k gold ring cast in a high-precision centrifugal machine won’t survive prolonged exposure to salt air without rhodium plating. Likewise, a bespoke platinum engagement ring line launched in a discount mall undermines its material narrative before the first customer walks in. The $280/sq ft rent on Rodeo Drive isn’t paying for pavement—it’s purchasing gravitational pull in the luxury ecosystem. For metalsmiths, that means choosing venues where the architecture supports the story your hands have forged: one of integrity, rarity, and enduring value. When Tiffany’s installed its first 1888 flagship on Union Square, it didn’t chase traffic—it created a destination. That principle hasn’t aged. It’s just been recalibrated for new zip codes, new metrics, and new generations of discerning buyers who measure worth not in carats alone, but in context.
Real-time lease data from CoStar Group confirms that venues with jewelry tenant retention above 70% over five years have seen average rent growth of just 2.1% annually—well below the national retail average of 4.8%. Stability, not speculation, defines premium real estate. And for jewelers whose products are measured in decades, not quarterly earnings, that stability isn’t a cost—it’s compound interest on reputation.
The metalsmith’s hammer doesn’t just shape metal—it sets rhythm, intention, and consequence. So does the lease agreement. Choose both with equal care.
For independent artisans, the path isn’t always owning a storefront. Many now leverage premium-venue partnerships: renting display cases inside curated concept stores like The Future Perfect (NYC) or The Line (LA), where rent is structured as a flat monthly fee ($3,200–$5,800) plus 8% commission—bypassing six-figure buildouts while gaining immediate credibility. These arrangements increased 63% in 2023 (RetailWire Artisan Report), proving that premium alignment can be leased, not bought.
One final metric: customer lifetime value (CLV). JA data shows CLV for premium-venue buyers averages $12,400 over 12 years—driven by repeat bridal, anniversary, and heirloom restoration purchases. Mall-based buyers average $3,100. That $9,300 delta pays for 5.6 years of Madison Avenue rent. Venue isn’t expense. It’s investment—with compounding returns measured in trust, not just transactions.
Whether you’re hand-forging a single titanium wedding band or managing a multi-state retail group, remember: the venue is the first setting for your jewelry. It holds the stone before the prongs do.
More Articles
 How to Choose a Wedding Band With a Twisted Design
 Citrine Engagement Rings Warm Golden Autumn Tones
 Ring Sizing Tips You Can Do at Home Accurately
 Clean Wedding Ring Safely at Home: 7 Proven Methods (2026)
 Jewelry Care FAQ: Wear and Sizing Guide
 Do You Wear Wedding Band On Inside Or Outside (2026)
 Celtic Wedding Bands Heritage and Meaning Explained
 Wedding Band Matching Rules: What You Really Need to Know
 How to Resize a Wedding Ring Without Damaging It
 How to Pair Engagement and Wedding Rings Together